TRUMP DID IT AGAIN — SENIORS 65+ GET A SURPRISE $6,000 TAX BREAK, BUT THERE’S A CATCH
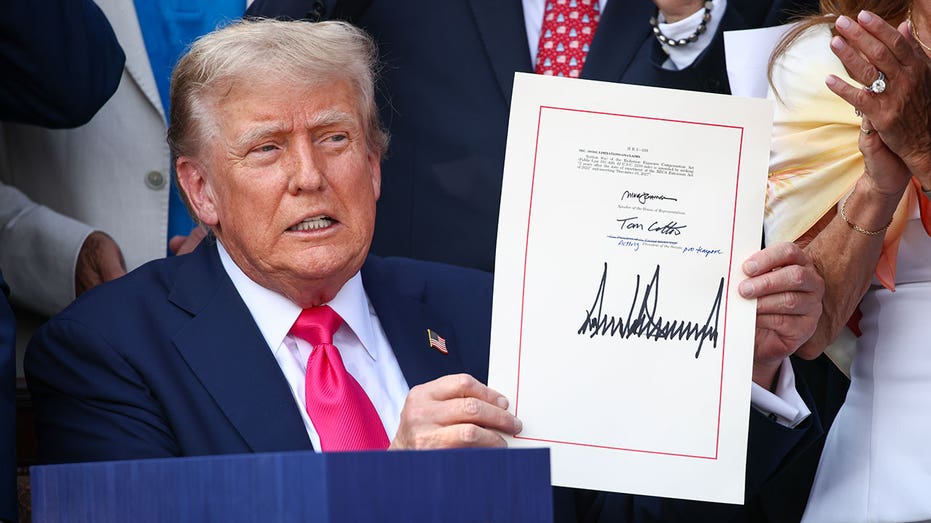
A new tax break is giving millions of older Americans a reason to look much more closely at their 2025 and 2026 tax returns.
Under the tax law President Donald Trump signed in 2025, eligible taxpayers age 65 and older can claim an additional deduction of up to $6,000 per person.
For a married couple in which both spouses qualify, that can mean up to $12,000 in additional deductions.
But there is one crucial detail that could easily get lost in the excitement:
This is not a $6,000 check from the government.
It is a tax deduction that can reduce the amount of income subject to federal income tax.
And depending on a senior’s income and tax situation, the actual savings can be considerably smaller than $6,000.
THE $6,000 NUMBER IS REAL — BUT IT ISN’T A CASH PAYMENT
The Internal Revenue Service says the enhanced senior deduction was created by the One Big Beautiful Bill and is available for tax years 2025 through 2028. Eligible taxpayers who are at least 65 by the end of the tax year can claim an additional $6,000 deduction per person.
That means a qualifying single senior could potentially claim:
$6,000 in additional deductions.
A married couple filing jointly, with both spouses age 65 or older, could potentially claim:
$12,000.
But “deduction” is the key word.
A deduction lowers taxable income. It does not reduce the tax bill dollar-for-dollar.
For example, a $6,000 deduction does not automatically mean a senior receives $6,000 back from the IRS.
The actual tax benefit depends on the taxpayer's circumstances, including income and tax bracket.
That distinction is important because social-media posts and viral headlines can make the provision sound like a direct government payment.
It isn't.
WHO QUALIFIES?
The IRS says taxpayers must be at least 65 years old by the end of the tax year to qualify. The deduction is available whether someone claims the standard deduction or itemizes deductions.
But higher-income taxpayers may receive less.
The additional deduction begins phasing out when modified adjusted gross income exceeds:
$75,000 for single filers
$150,000 for married couples filing jointly
The law reduces the $6,000 deduction by 6% of the income above those thresholds.
So the headline number is a maximum, not a guaranteed benefit for every American over 65.
That could make a major difference in how much a particular household actually saves.
WHY THIS IS GETTING SO MUCH ATTENTION
The provision arrived after Trump had repeatedly campaigned on providing tax relief to older Americans.
During his 2024 campaign and afterward, Trump promoted the idea of eliminating federal income taxes on Social Security benefits.
The final law, however, did not eliminate federal income taxes on Social Security.
Instead, it created the temporary enhanced senior deduction.
That difference matters.
A taxpayer can still have taxable Social Security benefits under existing federal rules, even while benefiting from the new deduction.
The deduction may reduce taxable income and, for some households, reduce the amount of Social Security that ultimately becomes subject to federal income tax.
But it does not make Social Security universally tax-free.
AND THIS IS WHERE THE “SURPRISE” COMES IN
For seniors who qualify, the new deduction is layered on top of the existing tax treatment for older taxpayers.
The IRS describes it as a new deduction in addition to the existing additional standard deduction available to seniors.
That means the potential tax benefit can be meaningful even though the government isn't simply mailing seniors a $6,000 payment.
Consider a married couple in which both spouses are over 65 and their income falls within the range for the full additional deduction.
They could potentially receive:
$6,000 + $6,000 = $12,000 in additional deductions.
Again, that is a reduction in taxable income — not $12,000 deposited into their bank account.
For retirees carefully managing taxable income, however, the distinction between taxable income and total income can have real consequences.
THE BENEFIT DOESN’T LAST FOREVER
There is another detail seniors should know.
The enhanced deduction is currently scheduled to apply for tax years 2025 through 2028.
Unless Congress changes the law, the special $6,000 deduction will not continue indefinitely.
That means eligible seniors may have several years to take advantage of it, but they should not assume the provision is a permanent change to the tax code.
The income phaseouts also mean the amount available can change as a taxpayer's financial situation changes.
A retiree who qualifies for the full deduction in one year could receive a smaller deduction in another if income rises.
WHAT ABOUT SOCIAL SECURITY?
This is perhaps the biggest source of confusion.
The new law does not abolish the federal income tax on Social Security benefits.
Instead, the additional senior deduction can lower taxable income and potentially reduce a retiree's overall federal tax liability.
For some seniors, that may also affect how much of their Social Security benefits are effectively exposed to federal income tax.
But the underlying Social Security taxation rules remain in place.
That is why saying “Trump ended taxes on Social Security” would go too far.
The more precise description is that the new law provides additional tax relief for qualifying seniors.
A BIG CHANGE — BUT NOT THE SAME FOR EVERYONE
The politics surrounding the law are likely to remain intense.
Supporters of the measure can point to a specific benefit written directly into federal tax law: an additional deduction of up to $6,000 for eligible taxpayers 65 and older.
Critics have emphasized that the provision is temporary and subject to income limits, and that it does not fulfill the broader promise of eliminating federal taxes on Social Security.
Both points are important for understanding what seniors actually received.
The headline number is $6,000.
The real-world benefit depends on the taxpayer.
And the money isn't arriving as a surprise check.
WHAT SENIORS SHOULD LOOK FOR
For Americans 65 and older, the practical question is no longer simply whether the $6,000 deduction exists.
It does.
The question is whether they qualify for all or part of it.
The IRS says seniors should pay attention to their age at the end of the tax year, filing status and modified adjusted gross income.
A single taxpayer with income below the phaseout threshold may qualify for the full deduction.
A married couple filing jointly may qualify for up to $12,000 if both spouses are eligible and their income remains within the applicable limits.
Higher-income taxpayers may receive only a partial deduction or none at all.
And because the provision is a deduction rather than a credit, the actual reduction in taxes owed will depend on the individual's broader tax picture.
THE BOTTOM LINE
So, did Trump give seniors a “massive gift”?
There is a real new tax benefit for millions of older Americans, but the phrase needs an important clarification.
It isn't a $6,000 government check.
It isn't an automatic tax refund.
And it doesn't make Social Security universally tax-free.
It is an additional tax deduction of up to $6,000 per eligible person, available for tax years 2025 through 2028 and subject to income-based phaseouts.
For a qualifying senior, that could mean a meaningful reduction in taxable income.
May you like
For a married couple, it could mean as much as $12,000 in additional deductions.
And for anyone hearing the viral version of the story, that distinction may be the most important surprise of all.